

Overplanning
An asset allocation or savings plan can stay on paper while conditions change. The cost is delayed implementation and no real feedback on whether it fits.
Wealth personality
ITAC
Structured planners who stay on course toward freedom.
Like a captain, you feel most confident when there is a clear course, a working plan, and enough room to adjust without losing direction. You like to know where your money is meant to go before taking the next step. This creates focus and helps you follow through on long-term goals. Under pressure, more planning can feel productive even when the real need is to make a small decision and learn from what happens.
Under stress, adding more structure can delay the next useful action, leaving plans untested and opportunities unavailable. The tension is that careful planning can become overplanning, delaying action until opportunities pass or real-world feedback never arrives.
“What important money decision has been planned well enough to act on now?”
Sounds like you?
01
I like to know where my money is meant to go before I act.
02
A clear plan helps me stay focused on long-term goals.
03
I can keep planning when a small step would teach me more.
How you make wealth decisions
The rhythm behind how you protect, grow, and use wealth.
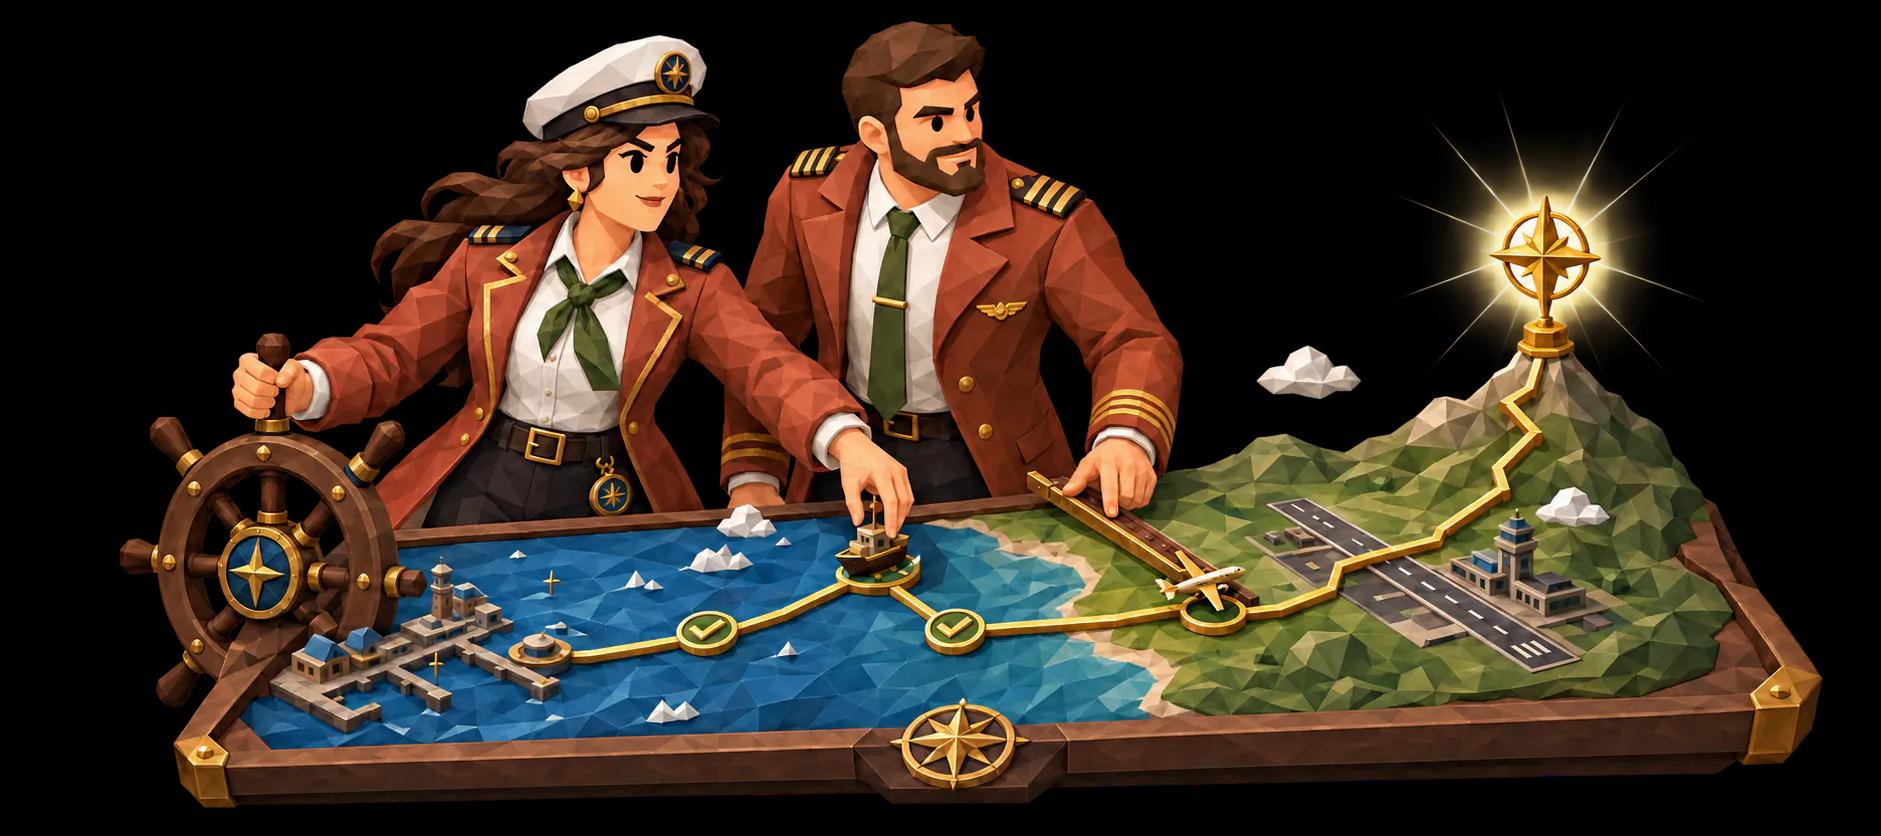
You protect wealth with dependable systems, clear priorities, and a plan for the unexpected.
Growth comes from staying on course and making deliberate adjustments over time.
Wealth supports the freedom to choose your direction and follow through on it.
Decision style
You set a goal, make a plan, and use structure to stay on track. This keeps you focused, but more planning can sometimes replace taking the next useful step.
Natural strengths
Strengths that may shape how you handle uncertainty, priorities, and long-term trade-offs.
Creates clear plans
Follows through consistently
Keeps long-term goals visible
Watch for this
Patterns worth noticing before they quietly run the decision.
An asset allocation or savings plan can stay on paper while conditions change. The cost is delayed implementation and no real feedback on whether it fits.
More structure can feel like progress, but it can delay funding a goal, investing surplus, or testing an assumption. Preparation replaces implementation.
Without a small real-world test, key assumptions about cost, demand, or risk remain theoretical. Plans improve only after they meet reality.
When money gets real
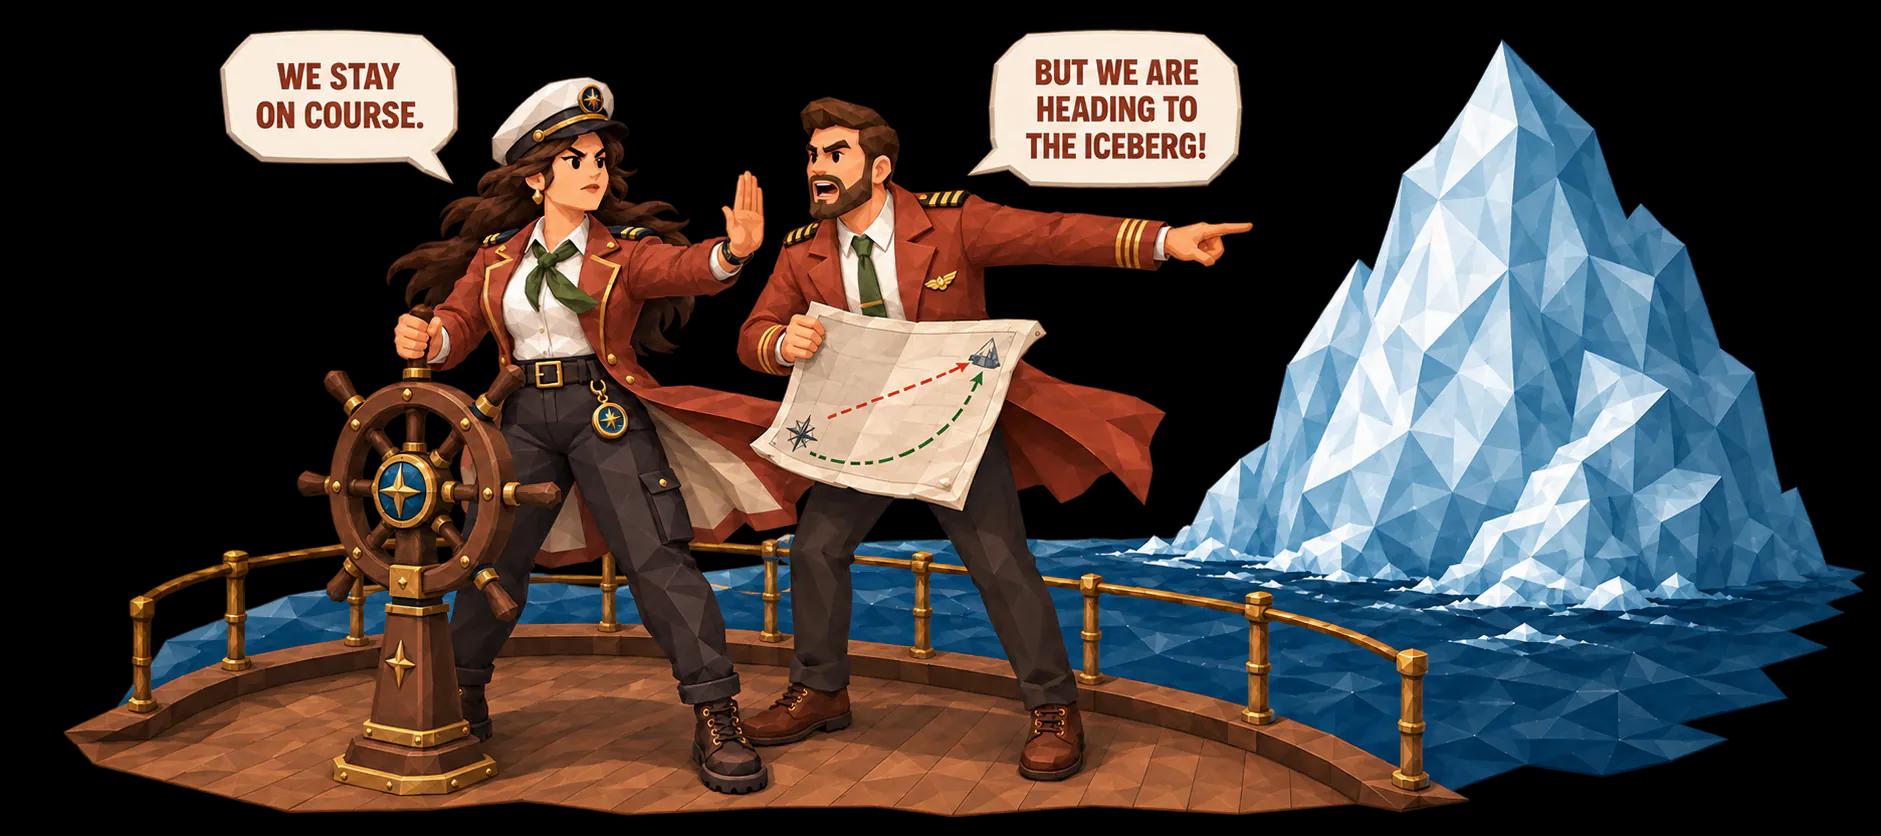
A well-prepared financial plan meets an unexpected change in income or timing. The tension is between staying disciplined and allowing real-world feedback to revise the route.
A useful tension to notice
Your structure is a strength when it gives you direction and room to learn. Build in review points so the plan can improve with reality.
What already serves you
You protect wealth with dependable systems, clear priorities, and a plan for the unexpected. Creates clear plans. Follows through consistently. These are strengths worth deliberately carrying forward.
What is worth questioning
Your structure is a strength when it gives you direction and room to learn. Build in review points so the plan can improve with reality.
A thought to carry forward
Use your plan to create direction, but let real-world feedback revise the route when it teaches you something new.
A question to sit with
What important money decision has been planned well enough to act on now?
WPTI is educational self-reflection, not investment advice, a financial recommendation, or a suitability assessment.