

Reducing future flexibility
Lifestyle inflation can absorb income that might otherwise preserve future flexibility. Present spending gradually raises the minimum cost of the life you need to support.
Wealth personality
ITNC
Flexible life-designers who make money serve a good life.
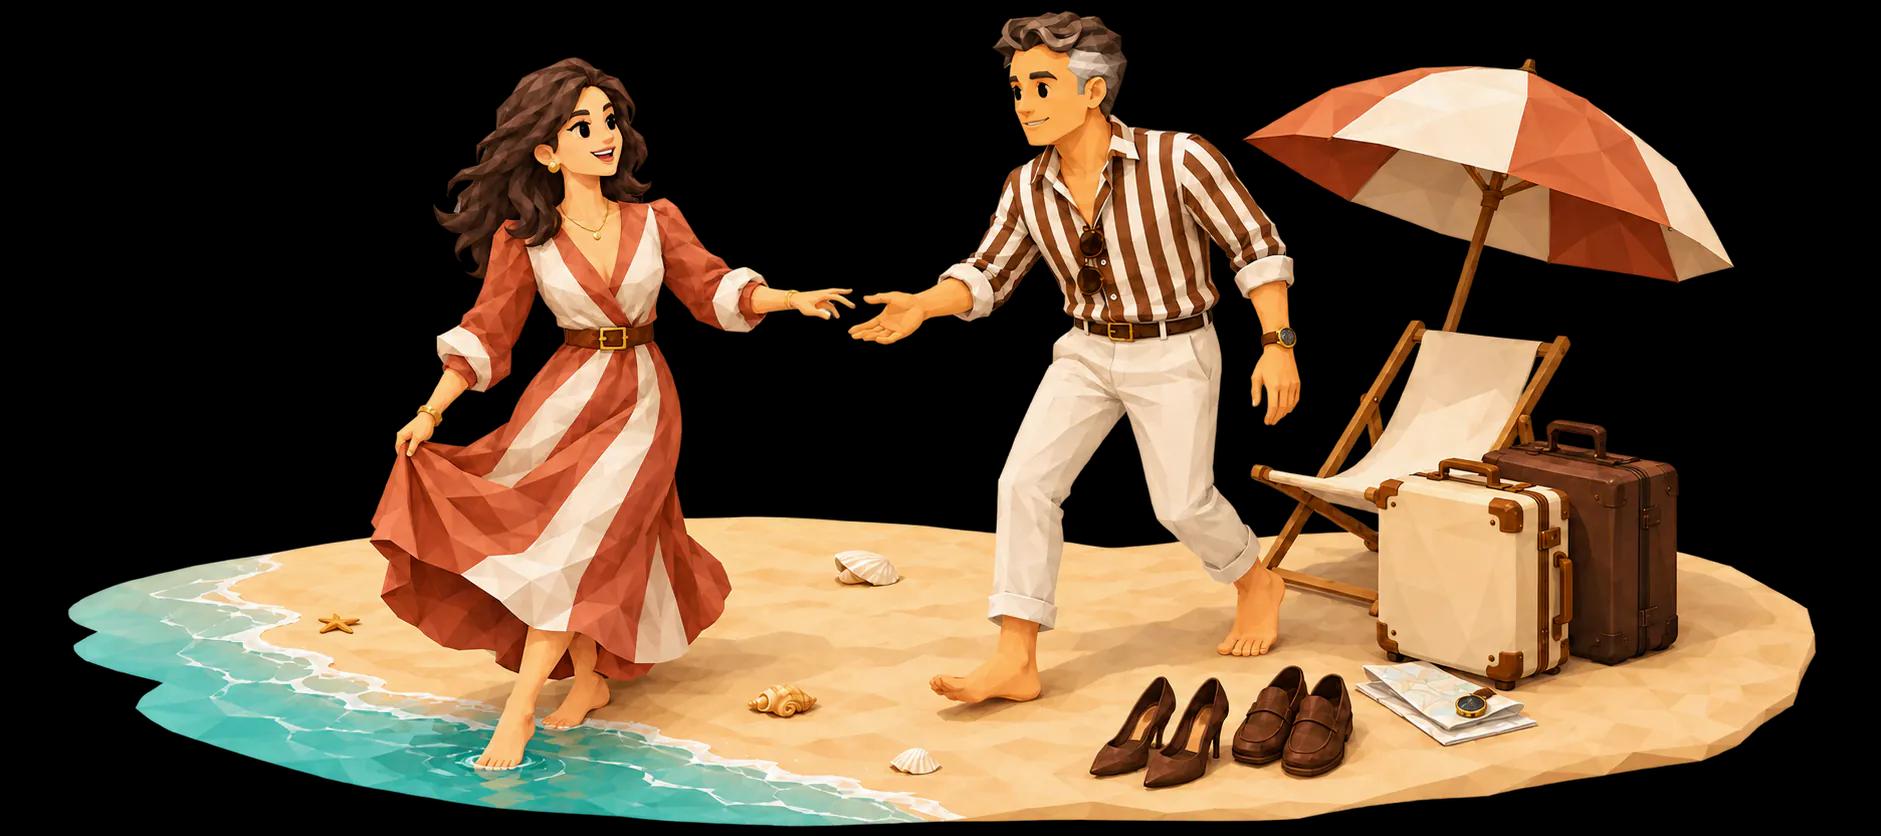
Like a lifestyle traveler, you judge money choices by the life they make possible, not only by the return they offer. Time, experiences, comfort, and freedom matter deeply to you. This keeps your finances connected to what you truly value. Under pressure, protecting freedom today can make it easier to delay the saving, debt reduction, or commitments that protect your choices later.
Under stress, protecting today’s freedom can mean postponing future commitments, which can gradually narrow the choices you want to keep open. The tension is that prioritising freedom today can quietly reduce future options when spending or flexibility is not matched by clear long-term commitments.
“What future choice are you protecting when you choose not to spend today?”
Sounds like you?
01
I judge money choices by the life they make possible.
02
I value time, experiences, and freedom as much as financial return.
03
I can put today’s freedom ahead of future commitments.
How you make wealth decisions
The rhythm behind how you protect, grow, and use wealth.
You keep enough flexibility to support essential priorities and leave room for life to change.
Growth creates more future choice and supports quality of life rather than becoming an end in itself.
Meaningful experiences, relationships, comfort, and freedom are central reasons to build wealth.
Decision style
You weigh choices against what matters most in your life and the freedom you want. This keeps money connected to your values, but today’s freedom can sometimes come before future needs.
Natural strengths
Strengths that may shape how you handle uncertainty, priorities, and long-term trade-offs.
Connects money to personal values
Adapts priorities as life changes
Maintains perspective beyond scorekeeping
Watch for this
Patterns worth noticing before they quietly run the decision.
Lifestyle inflation can absorb income that might otherwise preserve future flexibility. Present spending gradually raises the minimum cost of the life you need to support.
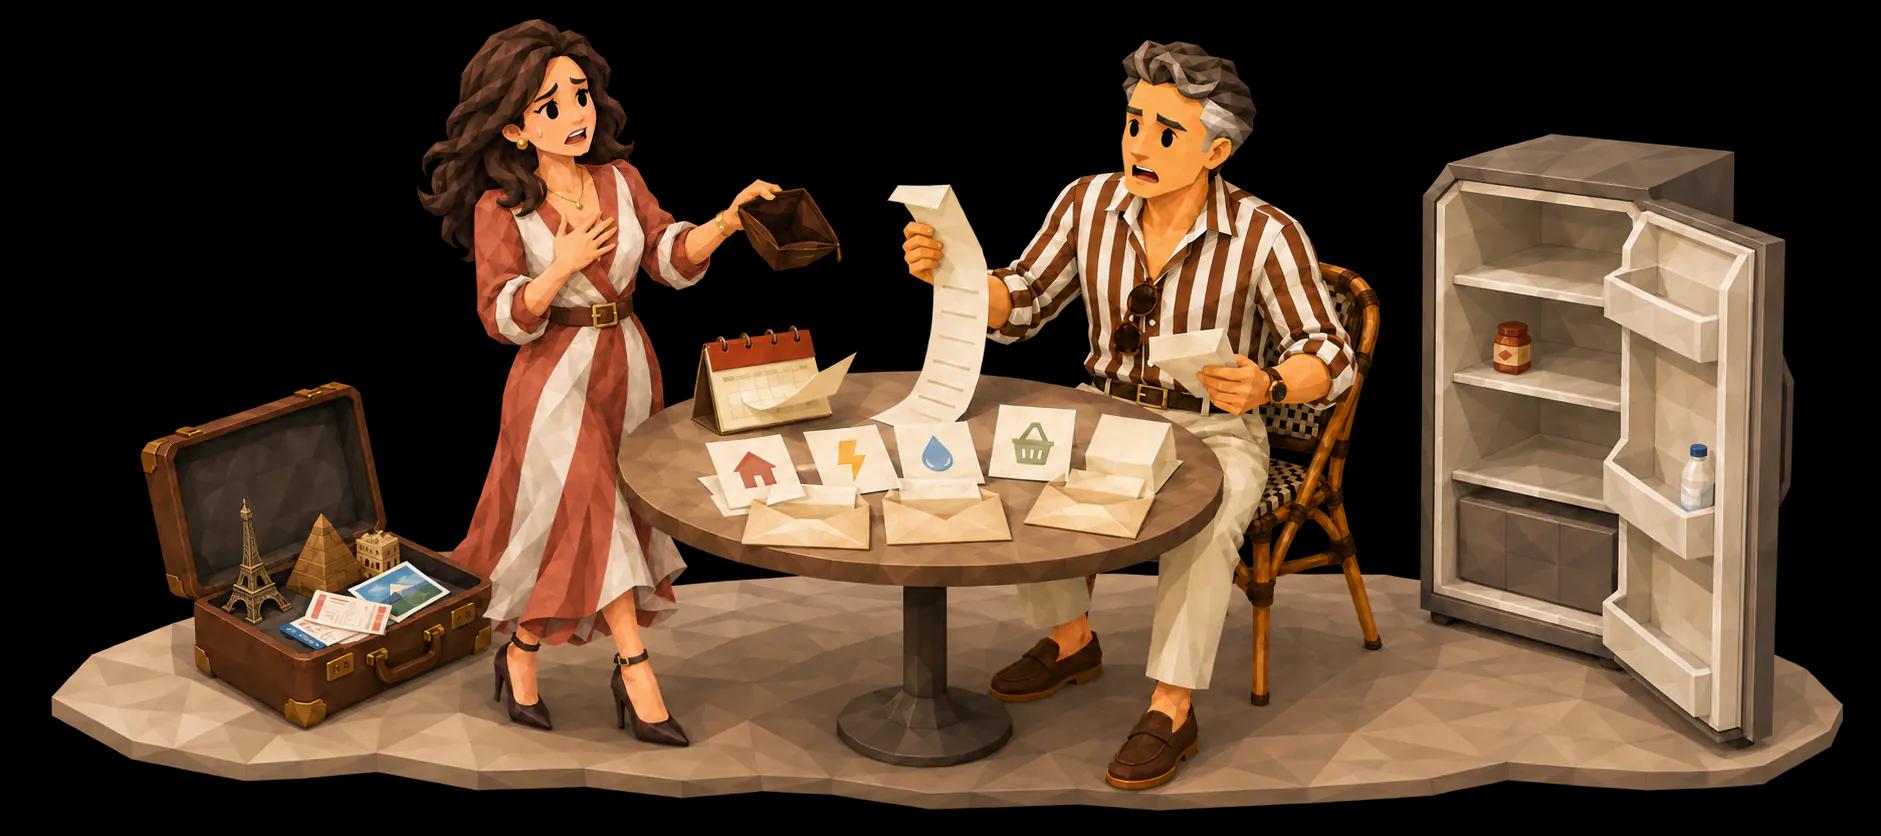
Deferring retirement savings, debt reduction, or long-term goals protects today's freedom. The later cash-flow commitment becomes larger.
Without a baseline for saving and future commitments, flexibility is financed by tomorrow. Long-term security weakens quietly.
When money gets real
A lifestyle choice feels meaningful now but affects future flexibility. The tension is between enjoying present freedom and preserving options for the future.
A useful tension to notice
Clear boundaries can make enjoyment feel more intentional, not more restricted, while preserving the choices you want for your future self.
What already serves you
You keep enough flexibility to support essential priorities and leave room for life to change. Connects money to personal values. Adapts priorities as life changes. These are strengths worth deliberately carrying forward.
What is worth questioning
Clear boundaries can make enjoyment feel more intentional, not more restricted, while preserving the choices you want for your future self.
A thought to carry forward
Use money to support the life you value today, but protect the commitments that keep future freedom available.
A question to sit with
What future choice are you protecting when you choose not to spend today?
WPTI is educational self-reflection, not investment advice, a financial recommendation, or a suitability assessment.